Your Estate Plan Is Not Finished When You Sign It: Why Proper Implementation Matters in Connecticut
Signing a will or revocable living trust is an important step in protecting your family. But an estate plan is only as effective as its implementation.
At Holland Law Offices, we believe Connecticut estate planning should go beyond preparing and signing documents. We work with our clients to help ensure that their assets are properly titled, beneficiary designations are coordinated with their estate planning documents, and—when avoiding probate is one of the client’s objectives—the estate plan is actually structured to accomplish that goal.
Retirement accounts provide an excellent example of why implementation matters.
IRAs, 401(k)s and similar retirement accounts are often among a family’s largest assets. Yet these accounts generally do not pass according to the terms of a will. Instead, they ordinarily pass according to the beneficiary designation maintained by the financial institution.
An outdated beneficiary designation can therefore undermine an otherwise carefully prepared estate plan.
A $500,000 IRA—and an Estate Planning Problem Decades in the Making
Consider an account owner who completed an IRA beneficiary designation in 1998 naming a spouse as beneficiary. The spouse subsequently died, but the account owner never updated the beneficiary designation.
Years later, when the account owner died, the $500,000 IRA did not pass directly to the children as expected. Instead, because there was no effective surviving designated beneficiary under the account’s governing documents, the IRA became payable to the estate and was subjected to probate.
The problem was not necessarily the estate planning documents themselves. The problem was implementation.
A beautifully drafted estate plan cannot accomplish its objectives if the assets have not been coordinated with it.
Beneficiary Designations Can Control Who Receives an Asset
Retirement accounts generally pass according to the beneficiary designation on file with the account custodian.
Consequently, signing a new will does not automatically change the beneficiary of an IRA or 401(k). Likewise, creating a revocable living trust does not automatically cause a retirement account to become governed by that trust.
The beneficiary designation must be considered as part of the overall estate plan.
This same principle can apply to other assets that pass by contract or beneficiary designation, including life insurance policies, annuities and certain financial accounts.
That is why estate planning should involve more than asking, “What does my will say?”
An equally important question is:
“How will each of my assets actually pass when I die?”
Connecticut Estate Planning and Probate Avoidance
For many Connecticut families, avoiding probate is an important estate planning objective.
A revocable living trust can be an effective part of a probate-avoidance strategy. Connecticut courts have recognized the use of revocable inter vivos trusts as probate-avoidance devices. But simply signing a trust does not magically place every asset into it.
The trust must be properly implemented.
For assets that are intended to be owned by the trust, ownership may need to be changed so that the appropriate trustee holds title. Other assets may be better handled through beneficiary designations, transfer-on-death arrangements, survivorship ownership or other planning techniques.
Retirement accounts require particularly careful treatment because changing the ownership of an IRA or qualified retirement account to a living trust generally is not how these assets are coordinated with an estate plan. Instead, the beneficiary designation ordinarily plays the critical role.
The correct approach therefore depends upon the type of asset, the client’s objectives and the overall estate plan.
Holland Law Offices Focuses on Implementation
At Holland Law Offices, our work with a Connecticut estate planning client does not simply end when the documents are signed.
We work with clients to understand how their assets are owned and how those assets are intended to pass at death. Where appropriate, we help clients coordinate the ownership and beneficiary designations of their assets with their newly created estate plan.
Implementation may include reviewing issues involving:
- Real estate and how title is held;
- Bank and investment accounts;
- Revocable living trusts and trust funding;
- IRAs, 401(k)s and other retirement accounts;
- Life insurance and annuity beneficiary designations;
- Primary and contingent beneficiaries;
- Joint ownership and survivorship provisions; and
- Other significant assets that could otherwise become subject to probate.
The objective is straightforward: the legal documents and the ownership of the client’s assets should work together.
A trust that is never properly funded may fail to accomplish an important probate-avoidance objective. A beneficiary designation that has not been updated in 20 years can produce a result completely different from what the client intended.
Estate planning is therefore not merely document preparation. Implementation is part of the planning.
Proper Titling Can Be Just as Important as the Trust Itself
Suppose a Connecticut client establishes a revocable living trust with the intention that certain assets pass outside probate.
If an asset that should have been transferred to the trust remains solely in the client’s individual name without another effective non-probate mechanism, that asset may still require probate administration at death.
The client may have an excellent trust—but the asset was never connected to it.
This distinction is easy to overlook.
Creating the trust establishes the legal structure. Funding and properly titling assets put that structure to work.
That is why Holland Law Offices works with clients on the implementation process rather than simply handing them a binder of signed documents and assuming the job is finished.
Retirement Accounts Require Different Planning
IRAs and qualified retirement plans deserve special attention.
Unlike a bank or brokerage account that may appropriately be retitled into a revocable trust during the owner’s lifetime, retirement accounts generally remain in the individual’s name. The estate planning attorney must instead consider how the beneficiary designation fits into the client’s overall plan.
Sometimes naming a spouse or children directly may be appropriate. In other circumstances, naming a properly drafted trust may accomplish important estate planning objectives.
The appropriate choice can depend upon many factors, including the beneficiary’s age, family circumstances, financial responsibility, potential creditor or divorce concerns, special needs, and applicable income-tax rules.
The important point is that the beneficiary designation should be intentional—not an old form that everyone forgot existed.
Primary and Contingent Beneficiaries Both Matter
Naming a primary beneficiary is only the beginning.
A well-coordinated estate plan should also consider what happens if the primary beneficiary dies first.
This is precisely where a contingent beneficiary can become important. Without an appropriate backup designation, the financial institution’s contract may determine where the account goes. Depending upon the governing documents, that could mean the account becomes payable to the estate and potentially subject to probate.
Beneficiary designations should therefore be reviewed as carefully as the provisions of a will or trust.
Life Changes Should Trigger an Estate Plan Review
Even a properly implemented estate plan can become outdated.
Connecticut residents should consider reviewing their estate plans and beneficiary designations following significant events such as:
- Marriage or remarriage;
- Divorce;
- Death of a spouse or another beneficiary;
- Birth or adoption of a child or grandchild;
- Significant changes in wealth;
- Sale or purchase of real estate;
- Retirement;
- A 401(k) rollover into a new IRA; or
- Opening or consolidating significant financial accounts.
A rollover deserves particular attention. When funds are moved from an employer retirement plan into a new IRA, the new custodian may require a new beneficiary designation. Clients should not simply assume that the beneficiary instructions associated with the old account automatically carry over.
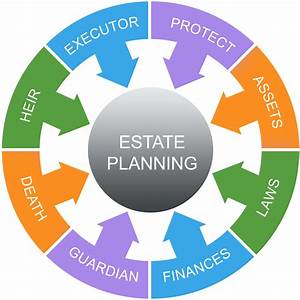
An Estate Plan Should Be Reviewed as a System
Effective estate planning requires looking at the entire financial picture.
A will, revocable living trust, power of attorney and health care documents are important. But so are deeds, account registrations, beneficiary designations, life insurance policies and retirement accounts.
They should not be viewed as unrelated pieces.
They should function as one coordinated estate plan.
For example, a client may tell an estate planning attorney that all assets should ultimately be divided equally among three children. The attorney then needs to consider whether the way the client’s assets are titled and the beneficiary designations currently on file are actually consistent with that objective.
Otherwise, what the documents say and what ultimately happens can be very different.
Avoiding Probate Requires More Than Signing a Trust
One of the misconceptions we frequently encounter is that signing a revocable living trust automatically avoids probate.
It does not.
A trust generally controls the assets that are actually connected to it through proper ownership, beneficiary planning or other appropriate mechanisms. Assets left outside the plan may still require probate.
This is why implementation is so important.
At Holland Law Offices, we want our clients to understand not merely what their estate planning documents say, but also how their assets will pass.
Our goal is to help ensure that when the time comes, the estate plan works the way the client intended it to work.
A Few Minutes Today Can Prevent a Significant Problem Later
The story of a $500,000 IRA governed by a beneficiary designation signed decades earlier illustrates a larger lesson.
Estate planning documents cannot be viewed in isolation.
Beneficiary designations, account ownership and property titling can determine whether assets pass directly to intended beneficiaries, are administered through a trust, or unexpectedly become part of a probate estate.
For Connecticut residents, a comprehensive estate plan should therefore address both planning and implementation.
Holland Law Offices Can Help
If you have an estate plan but are uncertain whether your assets are properly titled—or whether your beneficiary designations actually coordinate with your will or trust—this is an appropriate time for a review.
Holland Law Offices works with Connecticut individuals and families to create and properly implement estate plans designed around their particular circumstances. That includes reviewing how assets are titled, coordinating beneficiary designations with the estate plan, and helping clients implement appropriate probate-avoidance strategies.
If your trust has been signed but you are not certain whether it has been properly funded, or if you have not reviewed your retirement-account beneficiaries in several years, contact Holland Law Offices to schedule an estate planning review.
A good estate plan should not simply look correct on paper.
It should work when your family needs it.
Reference: 24/7 Wall St. (Aug. 15, 2026) “A $500,000 IRA Went Through Probate Instead of to the Kids, Because of a Beneficiary Form From 1998”